
Renters Insurance Tallahassee FL
Renters insurance in Tallahassee: the landlord's policy covers the building, and yours covers your belongings and your liability.
At InsuranceTallahasseeFL.com, Matt Williams, a licensed Florida agent, puts 80+ companies side by side for you.
- 80+ companies, side by side, same day
- Flood is not in most renters policies (FloodSmart)
- Owners live in 52.6% of Leon County homes (Census)
- Actual cash value subtracts wear and age (Florida CFO)
- Leon County is home to 299,048 people (Census 2025)
Before you set a belongings limit, see how cash value and replacement cost change a renters claim.
Renting and driving? Quote renters and car insurance on the same call.
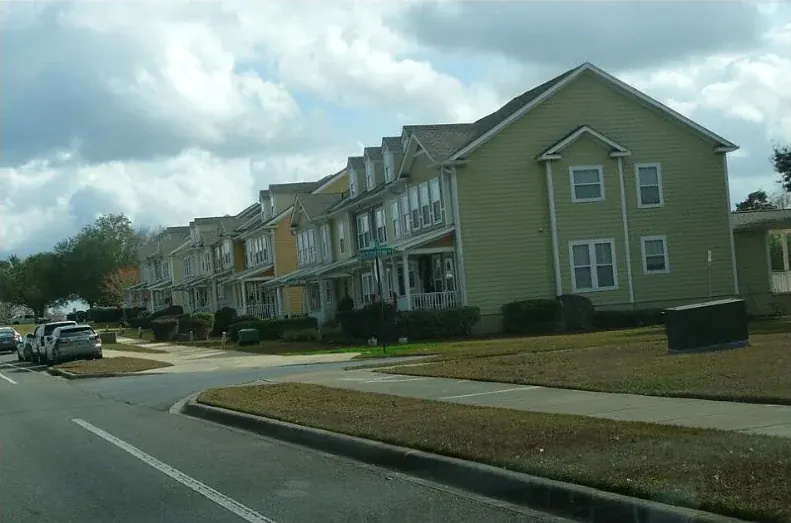
What a renters policy covers
Your things, not the building
The landlord insures the building; your policy covers what you own.
Liability comes along
A renters policy can include personal liability coverage.
Flood is separate
Most renters policies leave flood out, FloodSmart notes.
Read the details: the lease, the inventory and the fine print
The lease requirement is the floor, not the answer
A lease may name a liability limit or ask that the property manager appear on the paperwork. That tells you nothing about how much of your own property is covered, which deductible you are taking on, or how a loss would be valued. The building itself sits on the landlord's own policy, which is a different contract.
Ask to have the landlord requirement separated from your own decisions. Comparing is only meaningful when every option carries the same address, the same occupants and the same requested limits, rather than whatever default a website selected for you.
Add up what is actually in your apartment
Walk the rooms and think about clothing, furniture, kitchen things, electronics and everything else. Most people land on a far larger number than they expected, which is precisely why the default limit on a quick online quote is so often wrong.
Keep notes or photographs for yourself. Flag anything that may need separate treatment rather than assuming a general belongings limit handles it the same way. Ask how actual cash value and replacement cost differ in each option, because that single choice changes what you receive after a loss. If you work from the apartment, say so and ask about business equipment instead of assuming it counts as ordinary household property. Equipment for paid work may belong on a business policy for the work you do.
- Have the lease’s insurance section and move-in date available.
- Describe the people living in the rental and any roommate arrangement.
- Identify belongings or activities that need more than a general description.
Roommates, valuables and water need specific questions
Do not assume a roommate or their belongings are included because you share an address. Ask how each person should be handled under each option.
Identify jewelry, collectibles or anything else that may carry a special limit. Ask about the difference between a covered water event and flood, and whether separate flood protection is worth considering. Renting near Lake Lafayette or Lake Jackson? Leon County's flood map lookup shows the zone for your building. The answer depends on the actual contract, so bring the question to the review rather than trusting a broad label. Storm damage to the building is the landlord's question, though a tree that falls on the apartment can still ruin what is inside.
Renters coverage in three steps
Tell us the move in date and what the lease requires.
List what you own so the limit fits, then companies quote it.
Compare side by side; nothing is signed until you choose.
Read the details: dates, documents and the sequence
Your landlord insures the building. Not your things.
Renters Insurance Tallahassee FL: cheap to get wrong, cheap to get right
You have found the apartment, arranged the move, and the lease is asking for proof of insurance. It is tempting to buy the first policy that satisfies the requirement and move on.
The trouble is that the landlord policy covers the building, not your clothes, your furniture or your electronics. Those are yours to replace, all at once, if something happens. Renters cover is one of the few insurance products where a few dollars a month genuinely changes the outcome.
Have the lease ready and the move in date, and think about what you would actually need to replace. One call puts many companies on it, and you will know in five minutes.
Florida’s consumer guide describes renters insurance for personal belongings and personal liability; coverage depends on the policy selected. (Florida CFO renters guide)
Compare the request in a clear sequence
First the address, the occupancy, the lease requirement and the date you need cover to start. Then belongings, liability limits, deductibles and the loss settlement choices available. Want more liability than the renters policy holds? Ask about an umbrella above the renters liability limit.
Then put the options next to each other and ask what still differs. A licensed Florida agent can explain all of it without expecting you to know the terminology. If an application needs more detail or company review, you should hear that before assuming the quote is final or that your property manager has what they need.
- Understand the price. Review eligible credits and compare the total cost.
- Know the protection. Ask what is covered, what is excluded and what you would pay.
- Get a clear next step. Discuss documents, timing and follow-up with a licensed Florida agent.
- Keep the decision yours. Ask questions and review the options before choosing a policy.
Use your move in date as the planning date
Tell us when the lease begins and when the property manager wants evidence. If you are moving from another rental, ask how the old and new addresses should be handled.
Keep both sets of dates to hand rather than assuming an existing policy follows every part of the move by itself. A submitted request does not satisfy the lease. Get the policy, the effective date and the paperwork confirmed before you tell the landlord it is done.
A conversation does not commit you to a policy
You can call and ask what is needed without authorizing a purchase. Discuss the selections, read anything proposed and confirm the effective date before relying on it.
Do not send account numbers, identity documents or payment details through the general website enquiry. The first conversation exists to organize the request and tell you the next step. Cover is not created by reading this page, leaving a message, or receiving an acknowledgment from the website.
Keep the documents useful after the move
Once you have a policy, keep the declarations, the contact details and your inventory together. Check that the address and the named insured match what you discussed.
If you buy something significant, add a roommate, start working from home or move again, ask for a review. At renewal, compare what is listed against how you actually live now before assuming the selections still fit. Ten minutes of organizing makes the next conversation much shorter.
- Driving as well as renting? See the car, home and business requests on one Tallahassee call, or go straight to renters and car quotes on the same call.
- Buying a house instead of renting? Start the homeowners request with the roof date.
- Buying a unit near campus? Condo cover starts where the association's policy stops.
Check the Original Sources
Questions Worth Asking Before You Call
Does my landlord’s insurance cover my belongings?
Do not assume the building owner’s policy protects your possessions or personal liability. Ask the agent to review a renters request for your own belongings, use and lease requirements.
Can roommates share one renters policy?
That depends on the proposed policy and carrier rules. Disclose everyone living in the rental and ask who is insured and whose belongings are included before relying on a shared arrangement.
Can I get proof before my move-in date?
Call with the date and lease requirements. The agent must confirm availability, any remaining application requirements and the effective date; this website does not promise immediate issuance.
Still wondering about something? Call (850) 761-9992
Already renting with a policy?
Send its declarations page and companies can match the same limits for your new place.
Renting in Leon County, in figures
- 122,597Leon County households (2020 to 2024 estimate)
- 143,256Leon County housing units (July 2025 estimate)
- 52.6%Owner-occupied housing (2020 to 2024 estimate)
- 299,048Leon County residents (July 2025 estimate)
Source: U.S. Census Bureau; figures checked