On this page +
4-Point Inspection and Wind Mitigation: the key distinction
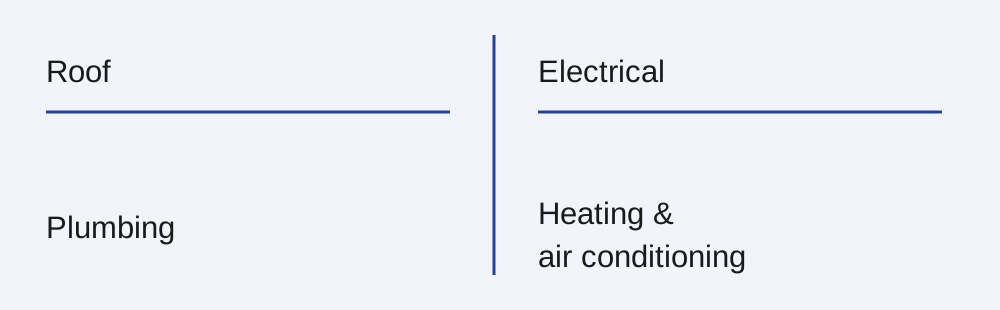
A four-point inspection reviews the roof, electrical system, plumbing, and heating and air conditioning.
The wind-mitigation review
Florida’s consumer guide identifies OIR-B1-1802 as the wind-mitigation inspection form.
Check what the carrier needs
- The exact report type and currently accepted form.
- Required photographs and supporting records.
- Inspector qualifications and how recent the report must be.
- Whether a repair or missing document needs separate follow-up.
Keep the reports with the property records
Save roof permits, installation invoices, inspection findings, and any follow-up correspondence together. An inspection report does not itself bind coverage or establish a claim outcome.
The reports answer different questions
A four-point report addresses major home systems, while a wind-mitigation report documents features relevant to wind resistance. Ask which report the insurer requested and whether both are needed for the particular request. The name of an inspection does not establish that the property is eligible or that a credit will apply. The report, carrier criteria and policy request need review together.
Collect existing records first
Have the complete report, its date and any supporting roof or improvement records available. If an inspector identified a concern, keep the follow-up repair documentation with it. Ask whether the existing report is acceptable before ordering another visit. Do not assume that a report prepared for a previous transaction satisfies a different insurer’s current requirements.
Use the report in the coverage conversation
An inspection may reveal questions about condition, but it does not replace a policy review. Ask how any required repairs, documents or underwriting decisions affect the requested effective date. Keep deadlines from the insurer’s letter visible. If the report contains an error, discuss the appropriate correction with the inspector rather than changing or omitting the information in an application. Keep the complete report rather than a single summary photograph. Its observations, date and supporting details may all matter to the review.
Helpful Tallahassee
and Florida resources
Ready to discuss the property or vehicle? Continue to home insurance requests.
Turn your next question into a clear next step.
Have your current documents nearby. Tell a licensed Florida agent what you want to protect, what concerns you and when you need an answer.
Last reviewed:
Sources for this page
- https://www.myfloridacfo.com/division/consumers/understanding-insurance/homeownersinsuranceoverview