A Florida insurance guide for Tallahassee readers

Tallahassee Tree Damage and Home Insurance

The short version

Tallahassee Tree Damage and Home Insurance comes down to policy wording, and that wording decides how a claim goes long before a limb falls. Trimming, removal before a storm and damage after one are separate questions. One call explains your policy's wording and puts your home in front of many companies for same day quotes.

Big oaks near the house? Bring them up when you compare home quotes.

Call (850) 761-9992; a licensed Florida agent walks you through it.

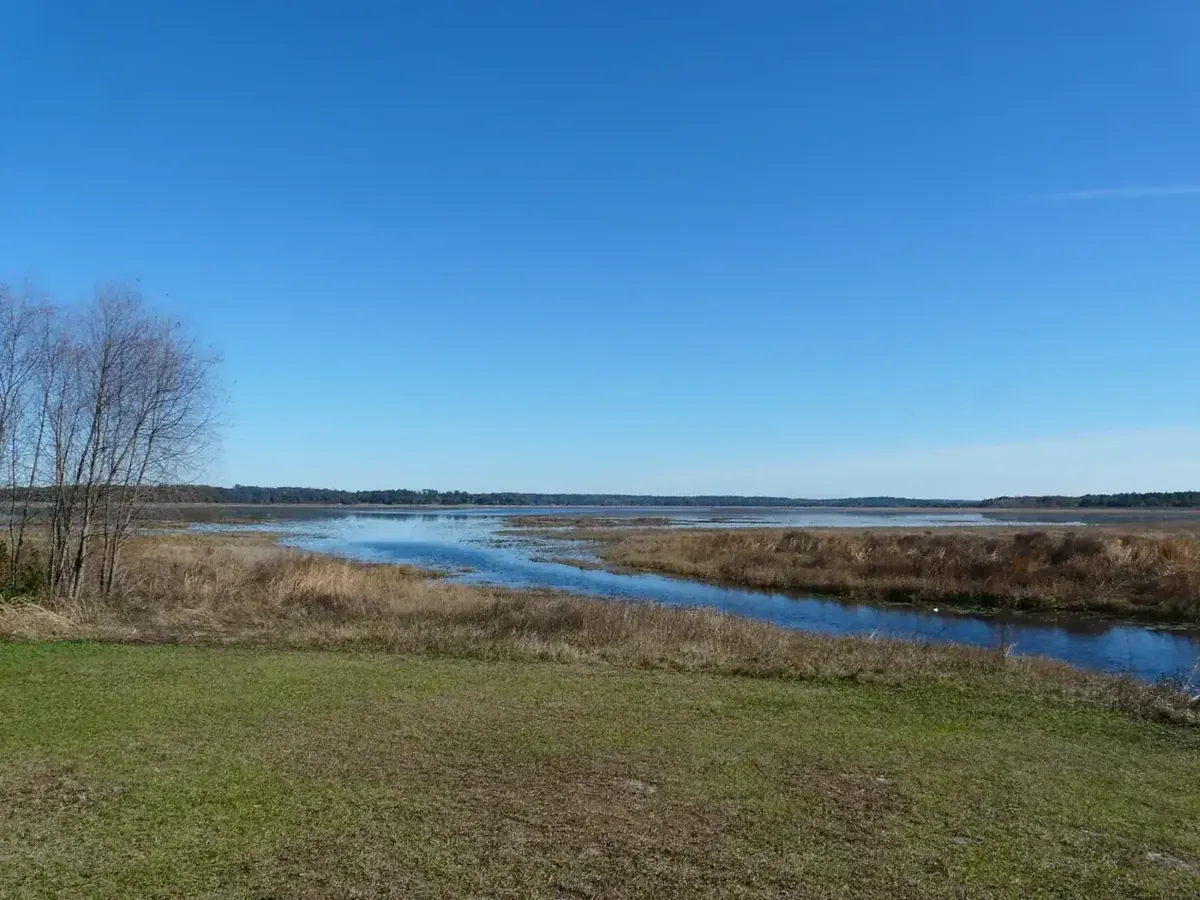
Lake Jackson viewed from Sunset Landing, Leon County
Lake Jackson, Leon County.

On InsuranceTallahasseeFL.com, Matt Williams, a licensed Florida agent, explains how home insurance treats a tree that falls on a Tallahassee house. The tree is not the question. Your policy wording is.

Tallahassee Tree Damage and Home Insurance: the wording decides the claim, not the tree

When a tree comes down, what your homeowners policy actually says matters more than the size of the tree. Where it stood, what it hit and how your wording treats structures, vehicles and debris can each change the answer, so it pays to know that wording while the weather is calm. A limb through a parked car usually goes to the car policy rather than the home policy.

The city's own urban forestry guidance treats tree condition and maintenance as part of preparing a canopy that stands up better to storms. Keeping a simple record of that care costs you nothing, and it is exactly what you want on hand if a claim or an underwriting review ever comes up.

Tallahassee’s urban-forestry guidance emphasizes tree condition and maintenance as part of preparing a more storm-resilient urban forest. (City of Tallahassee urban forestry)

Past storms give context, your own policy gives the answer

Recent storms are a good reason to review your coverage now, not a forecast of your next claim. Hurricane Michael in 2018, Idalia in 2023 and Helene in 2024 each have National Weather Service reports covering wind in Leon County, and the links below are worth a read.

A storm report describes a region, though. It cannot tell you how your own policy treats a limb on the roof or an oak across the driveway. That answer lives in your wording, and the calm stretch between storms is the easy time to go through it. The homepage's hurricane deductible calculator turns a storm deductible into dollars before you need it.

Hurricane Michael struck the Florida Panhandle in October 2018; the NWS post-storm report includes Leon County wind, rainfall, and damage observations. (NWS Tallahassee, Hurricane Michael)

Hurricane Idalia made Big Bend landfall on August 30, 2023. NWS reported more scattered or isolated wind impacts in eastern Leon County. (NWS Tallahassee, Hurricane Idalia)

Hurricane Helene made Big Bend landfall on September 26, 2024. The NWS event report includes wind observations in Leon County. (NWS Tallahassee, Hurricane Helene)

Four records that turn a worry into a specific answer

Have these on hand and a five minute call covers your actual home instead of a hypothetical one. Gather what you already have. If something is missing, say so and ask what matters.

  • Any tree or limb a qualified professional has flagged as a concern.
  • Maintenance already completed, plus any recommendations still outstanding.
  • Photos of the property, and records of earlier damage or repairs.
  • The policy wording you want explained on structures, vehicles or debris.

Roof repairs after a limb strike also belong in the roof file companies ask to see. A 4-point inspection report is often part of that file.

Describe it once, get your wording explained and compared

Tell us where the tree stands, what sits near it and the situation that concerns you. We explain the actual wording of your policy rather than letting you assume every kind of tree damage is handled the same way.

Some agencies represent a single company, which means one set of wording and one quote. We are independent and represent many, so the same description can go to many companies for same day quotes, side by side. Calling five agencies would mean telling the story five times.

A qualified eye for the tree, a clear answer on the policy

You get further, faster, when each question goes to the right person. A mature tree is part of many Tallahassee properties, but a photograph cannot establish its condition or predict a covered loss. Acreage carries more of them, which is why Woodville's rural lots and tall pines get their own page. Condition questions belong with qualified help, so keep any inspection or maintenance information close.

For the insurance side, name the property, the policy and the situation you are concerned about, and we take it from there. Do not assume every tree-related expense is treated the same way. Ask.

Know whether it is maintenance or a loss before the bill arrives

Sorting this out early could spare you an unwelcome surprise later. Routine trimming, removal before a storm and damage after an event each raise a different question. We identify the provisions that apply to your concern, including any limits or exclusions, so nothing rests on assumption. Once a loss is covered, whether the repair is paid at cash value or replacement cost decides the check. Rising water after the same storm is a separate flood question, covered in Leon County's flood zone lookup.

A tree standing near your house does not by itself establish any particular coverage result. If an insurer has already sent you a request, bring the complete notice and its deadline to the call. Talking to us does not extend that deadline, so keep working to it.

Your home gets its own answer, not the neighborhood's

The answer that matters is the one for your address. A neighborhood canopy or a regional storm history gives context, not an answer for an individual home. Describe the structures that could be affected and keep the relevant records ready in case a claim or underwriting review is involved. Own a rental under big oaks? The landlord policy on it has its own wording to check. Renters should know the building is the landlord's question, while your belongings sit on your renters policy.

If you have a loss to report, ask us how to contact the carrier. And to be clear about what this page is not: it does not determine fault between neighbors, and it does not replace professional advice about a hazardous tree.

Ready to talk about your property? Have your tree wording explained on a home quote call.

See other prices before you renew

Give your details once. A licensed Florida agent compares companies for Tallahassee, Leon County and the towns nearby, and the choice stays with you.